

How Income Protection Insurance Can Safeguard Your Financial Future
Income protection insurance is a type of insurance policy designed to replace a portion of your income if you are unable to work due to illness or injury. This financial safety net can help cover essential living expenses, such as mortgage repayments, utility bills, and daily costs, ensuring you maintain your standard of living during tough times. - read more

Income Protection Insurance for Australian Adults: How It Works and What to Consider
Income protection insurance can help replace part of your income if illness or injury prevents you from working. For Australian adults with regular expenses, dependants or long-term financial commitments, understanding how this cover works can be an important part of financial planning. - read more
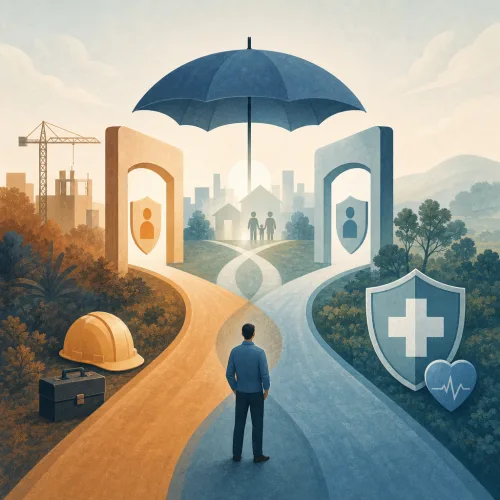
Income Protection Insurance and Workers Compensation in Australia: Key Differences
Income protection insurance and workers compensation can both provide income support after illness or injury, but they work in different ways. This guide explains the key differences for Australian employees, contractors and self-employed workers. - read more

Income Protection vs Life Insurance: How They Work Together
Income protection and life insurance are both designed to reduce financial pressure when major life events affect a household. They do different jobs: one can help replace income if illness or injury stops you working, while the other can provide a lump sum to beneficiaries if you die. - read more

Income Protection vs TPD Insurance: What's the Difference?
Income protection insurance and total permanent disability insurance both help provide financial support if illness or injury affects your ability to work, but they are designed for different situations. Income protection generally provides regular payments during a temporary incapacity, while TPD insurance provides a lump sum if you are permanently unable to work under the policy definition. - read more
No comments yet. Be the first to share your thoughts.