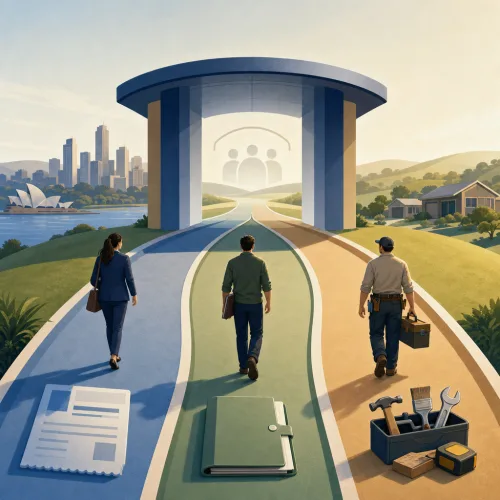
Income Protection Insurance for Employees, Contractors and Self-Employed Workers
Income protection insurance can work differently depending on whether you are a PAYG employee, contractor, sole trader, freelancer, gig worker or small business owner. Your employment structure may affect income evidence, policy design, premiums, exclusions and claim documentation. - read more
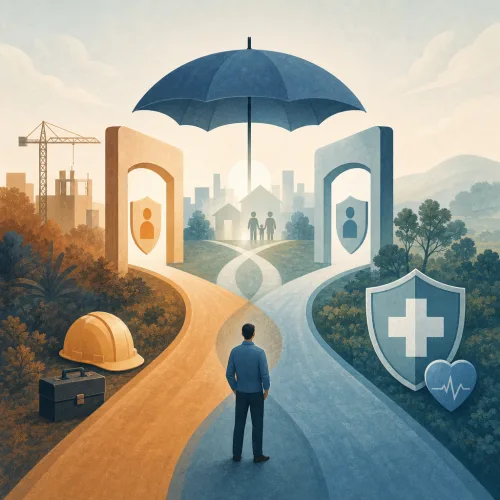
Income Protection Insurance and Workers Compensation in Australia: Key Differences
Income protection insurance and workers compensation can both provide income support after illness or injury, but they work in different ways. This guide explains the key differences for Australian employees, contractors and self-employed workers. - read more

Pre-Existing Conditions and Income Protection Insurance in Australia
Income protection insurance can provide replacement income if illness or injury prevents you from working. If you have a pre-existing medical condition, the application, policy terms and claims process may need closer attention because insurers assess health history when deciding whether to offer cover and on what terms. - read more

Preparing for the Unexpected: Why Income Protection is Essential for Financial Security
Life's unpredictability can often bring unforeseen challenges, particularly when it comes to our finances. One day you might be climbing the career ladder, the next you could find yourself unable to work due to illness or injury. This is where income protection insurance steps in, serving as a financial safety net that ensures you can continue to meet your living expenses, even when the unexpected happens. - read more

Income Protection vs Life Insurance: How They Work Together
Income protection and life insurance are both designed to reduce financial pressure when major life events affect a household. They do different jobs: one can help replace income if illness or injury stops you working, while the other can provide a lump sum to beneficiaries if you die. - read more