
Income Insurance Australia :: Articles

Types of Insurance Policies Every Business Owner Should Consider

What insurance policies are essential for business owners to consider?

Types of Insurance Policies Every Business Owner Should Consider

The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.

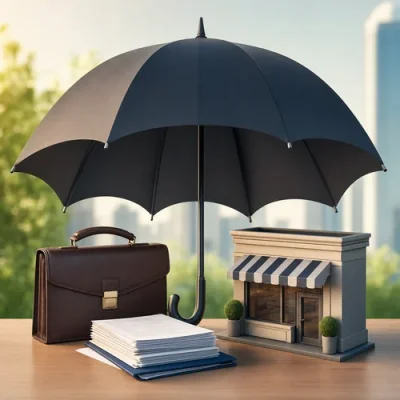
Protecting business investment with insurance is a critical part of every sensible business owner's business plan. Insurance protects businesses from unexpected financial risks due to natural disasters, accidents, liabilities and losses, which may run in to thousands.
Here are some insurance policies every business owner should consider to protect his investment as well as to ensure smooth running of his business.

Liability insurance

Business liability insurance covers the compensations and legal hassles resulted from the accidents, injuries, damage and loss caused by the business to third parties. There are three major types of liability insurance:
  1. Public liability insurance

    Public liability insurance protects your business against financial risk of being found liable for death, injury, loss or damage of property caused to the third party due to your negligence.
    For example, if a customer slips and falls due to wet floor at your business premises and gets injured, he may sue you and claim for compensation.
    Public liability insurance helps you during this kind of situations by taking care of legal and medical costs.
  2. Product liability insurance

    If your business involves in manufacturing, selling, or supplying goods, you should consider product liability insurance.
    It protects your business against financial loss as result of defective product that causes injury or bodily harm to the customer.
  3. Employers' liability insurance

    As a business owner, you are responsible for the health and safety of your employees while they are at work.
    An employee being injured while on the job, can file a compensation claiming that he should be given medical help and wage replacement while in recovery.
    This insurance protects you from the liabilities arising from disease, fatality, or injury to employees resulting from workplace conditions or practices.

Professional indemnity insurance

Professional indemnity insurance is a special type of liability coverage for professionals like accountants, architects, engineers, lawyers, insurance brokers and financial advisers.
In case of any faulty advice/service rendered by these professionals that causes damage to the client, the professionals are legally liable to pay compensation, if the client sues them. Having this particular policy, can help you face these legalities as well as the monetary claims.
For example, a patient may sue a physician for faulty diagnosis or improper treatment.

Business assets insurance

Business assets insurance covers the business assets such as buildings, premises, equipment, vehicles, stocks, and contents against losses arising from theft, fire, flood, natural disasters or other damages.
It provides financial assistance to rebuild or repair business property so that operations continue with as little disruption as possible.

Business interruption insurance

Your business operations may be interrupted due to sudden damage caused by natural disasters or any other accidents.
As it takes time to restore your business operations and generate profits, having business interruption insurance will offer cover for the loss of income, continuing fixed costs and other expenses associated with closure of your business.

Personal insurance

As a business owner, you should take a personal insurance policy as you are the key person in the business.
Personal insurance policy covers you against the risk of death, injury, accident or illness.
It provides income replacement, creates liquidity to pay-off debts and estate taxes on behalf of you.
Having known the different types of insurance policies and their benefits, you can either opt for selected policies or a comprehensive business insurance cover, which is customized as per your business needs. Select an appropriate insurance coverage and protect your business.

Published: Sunday, 1st Aug 2021
Author: Paige Estritori

Rate this article

0 Comments

No comments yet. Be the first to share your thoughts.


Income Protection Articles

Mental Health and Income Protection Insurance in Australia
Mental health conditions can affect income protection insurance applications and claims, but outcomes vary. This guide explains disclosure, underwriting, exclusions, claim evidence and practical steps for Australians comparing cover. - read more
Income Protection Insurance and Workers Compensation in Australia: Key Differences
Income protection insurance and workers compensation can both provide income support after illness or injury, but they work in different ways. This guide explains the key differences for Australian employees, contractors and self-employed workers. - read more
Income Protection Insurance for Australian Adults: How It Works and What to Consider
Income protection insurance can help replace part of your income if illness or injury prevents you from working. For Australian adults with regular expenses, dependants or long-term financial commitments, understanding how this cover works can be an important part of financial planning. - read more
Income Protection Through Superannuation and Salary Continuance Insurance Explained
Income protection through superannuation, salary continuance insurance and standalone income protection can all help replace income if illness or injury stops you working, but they differ in ownership, funding, tax treatment, flexibility and claims access. - read more
Pre-Existing Conditions and Income Protection Insurance in Australia
Income protection insurance can provide replacement income if illness or injury prevents you from working. If you have a pre-existing medical condition, the application, policy terms and claims process may need closer attention because insurers assess health history when deciding whether to offer cover and on what terms. - read more

Insurance News

Diagnosis timing is not the only test for income cover
12 Nov 2026: Paige Estritori
A recent income protection dispute has put fresh attention on a difficult but important issue for Australian workers: a medical condition may be treated as pre-existing even where a formal diagnosis comes later. The case, reported on 9 November 2026, involved a prostate cancer claim that was declined after the Australian Financial Complaints Authority accepted that earlier medical warning signs and specialist investigations were enough to trigger a pre-existing condition exclusion. - read more
Why Claims Communication Is Back in the Spotlight
05 Nov 2026: Paige Estritori
A new Life Code Compliance Committee inquiry has put fresh attention on the way life insurers manage longer-running income protection insurance and total and permanent disability claims, finding that clearer communication and earlier information requests could reduce avoidable stress for people waiting on claim decisions. - read more
Why Mental Health Cover Is Back in the Income Protection Spotlight
29 Oct 2026: Paige Estritori
Australia’s life insurance industry has moved mental health cover back to the centre of the affordability debate, after the Council of Australian Life Insurers released its response on 30 September 2026 to the independent review of the Life Insurance Code of Practice. For workers who rely on income protection insurance, the issue is practical: mental health conditions can affect earning capacity just as seriously as physical illness, but changes designed to keep premiums manageable may also alter what is covered. - read more
Why Super Service Standards Matter for Your Income Protection
17 Sep 2026: Paige Estritori
ASIC’s continuing focus on superannuation member services has put another practical issue in front of Australian workers: insurance inside super is not just about whether cover exists, but whether members can understand and use it when they need help. Recent regulatory attention on trustee administration, communication and claims support is a timely reminder for anyone relying on salary continuance or income protection benefits through their fund. - read more
Advice Changes Could Make Income Cover Easier to Understand
10 Sep 2026: Paige Estritori
Australia’s financial advice reform agenda has taken another important step, with industry attention turning to how simpler, more accessible guidance could help consumers make better decisions about insurance. For workers who rely on income insurance or salary continuance cover, the issue is more practical than political: many people hold cover they do not fully understand until illness or injury forces them to test it. - read more

Start Here !
disability protection
Apply now for your free Insurance assessment and price comparisons!

Start Here:

First Name:
Postcode:

All quotes are provided obligation-free by a participating broker from our national referral partner network. We respect your Privacy.
